While skimming through my macro-related TradingView layouts, “searching for inspiration”, I stopped the moment the Russell 2000 chart caught my eye. For two reasons.
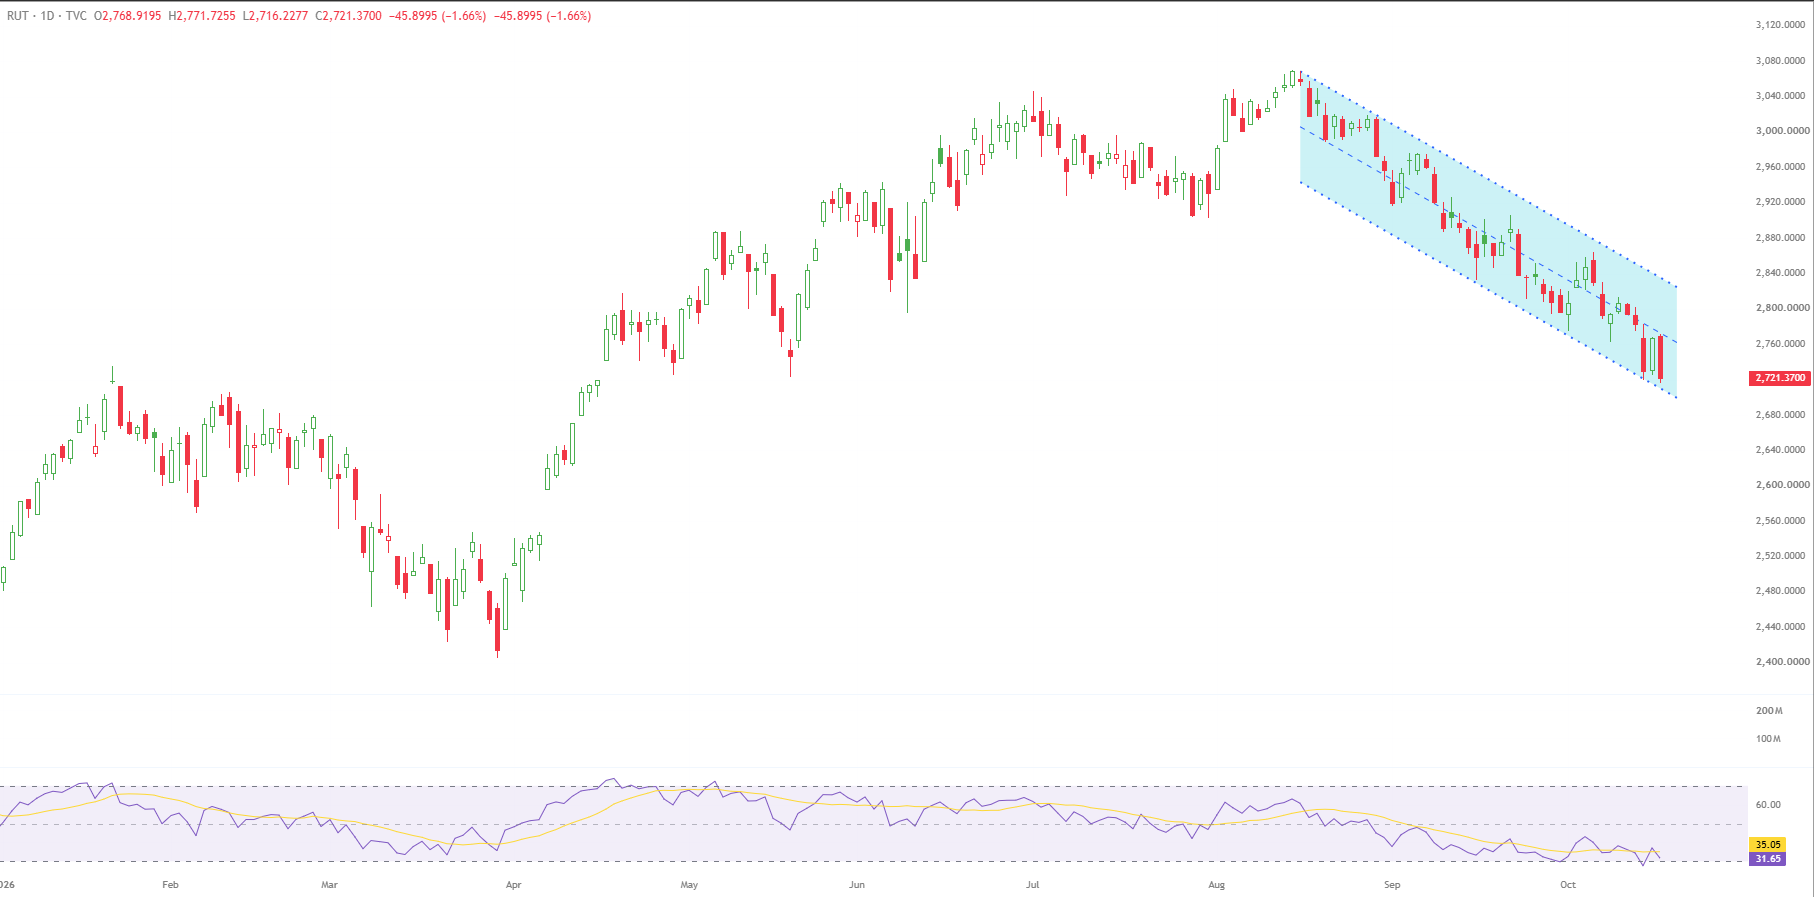
First, since early August, it has been depicting a solid downtrend, with lower highs and lower lows. Textbook style.
Second, this tells me that the mid-layer of the US economy is struggling... perhaps even cracking. Pick your adjective.
While the other two majors, the S&P and Nasdaq, managed to drift sideways within a range and eventually claim new all-time highs, Mr Russell has arguably been the weakest link.
The headwinds are massive, and the “real economy” is feeling the pain:
- (i) I have come across comments suggesting that some of the negative effects of the 2025 tariffs soap opera on consumer prices are proving rather persistent;
- (ii) the inflation skeleton is now running wild and proving difficult to corral anytime soon;
- (iii) Hormuz seems ready to renew its licensing rights for another dozen seasons of drama; and last but not least,
- (iv) the bond market is being heavily guarded by its vigilantes, leaving little room for anyone — now including Europe — to go their own way and hope for the best.
For me, this is a very challenging backdrop. Yet, it may well be an iceberg hiding opportunities for the patient but decisive speculator.
Energy keeps defying the odds and marching higher, despite a challenging back-to-school month, while Financials have recently caught a favourable wind from the latest drama surrounding the higher-for-longer rates narrative.
Eight Out Of Eight, And Counting
If I were to speculate on the short side of things, which I have rarely done throughout my trading journey, the semiconductor dam looks like an interesting place to poke a few more holes.
It’s been painful to watch a sector that propelled the market to such exuberance at the close of the first half being beaten up so consistently.
For now, it seems that the back of the peloton has new customers, ones who were anything but used to riding at the back, let alone dragging the markets down with them.
Although I had been seeing calmer winds from Korea, this past week felt different.
The KOSPI is approaching dangerous levels last seen in late July, when it finally managed some damage control and halted the free fall from its peak above 9,000.
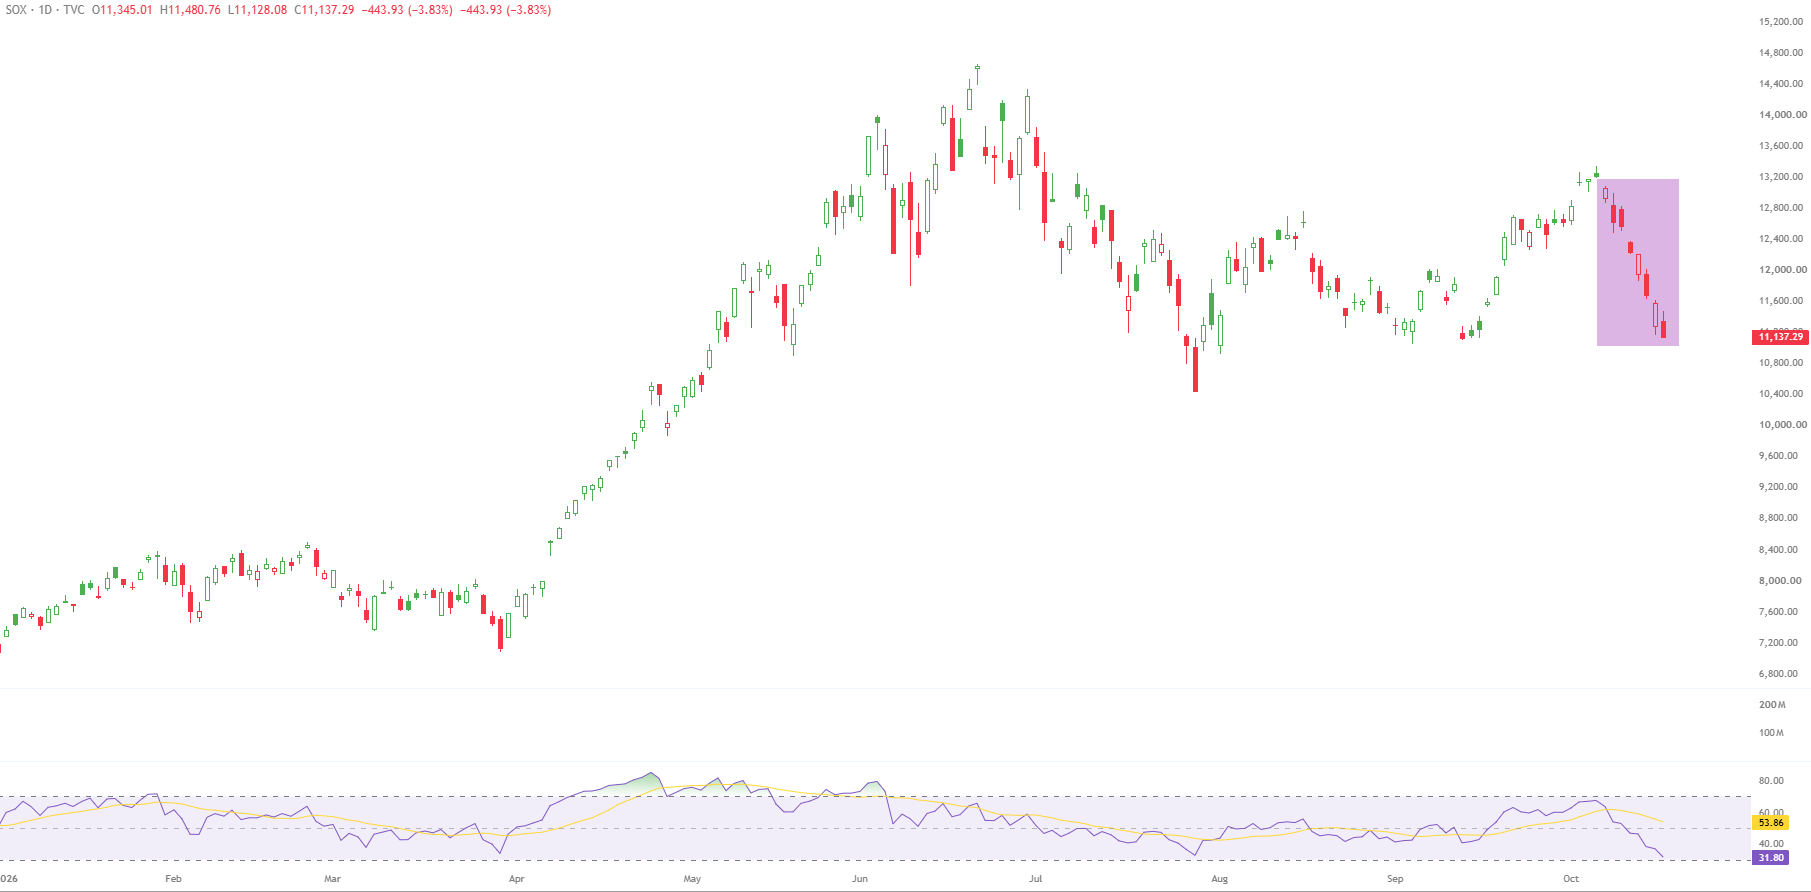
As of today, the SOX has recorded eight straight sessions in the red. The best it could manage was to close above its opening price on some of those sessions. You can spot them in the chart below as red hollow candles.
Traffic Control Update
In the coming weeks, I will be interested to see how Q3 earnings unfold. Popcorn is a must, as always.
More than the earnings themselves, it is the market reaction — be it silent, exuberant, or even panicky — that I will be recording in my own data memory.
At this precise moment, I am letting my positions fight this uphill battle, without tinting their performance with my own colours, but rather with the market’s... because that is the palette that should always be used, like it or not.